liveUpdated 20 minutes ago
Jitters across equity markets are sending money into fixed income, with Western bond markets rallying strongly on Thursday.
By Shaurya Malwa, James Van Straten, and Omkar Godbole
Share this post
With U.S. stocks adding to early losses, bitcoin has lost the $80,000 level for the first time since mid-September.
Trading at $79,950, it’s now lower by 3.5% over the past 24 hours.
The Nasdaq is down 1.4% and S&P 500 0.6%.
Government bond yields, meanwhile, are at session lows, the U.S. 10-year now down 15 basis points to 5.04%, its softest level in about one month.
Share this post
Bitcoin BTC$80,791.18 is trading at $80,500 shortly after the open of U.S. stocks, down 2.9% over the past 24 hours. It’s traded down to just dollars above $80,000 in recent minutes, with buyers stepping in to prevent a $79K handle for the first time since mid-September.
For the moment, the worst fears of the tech sector haven’t come to fruition, the Nasdaq slipping just 0.9%.
Small gains for Microsoft, Apple, and Google are masking the destruction going on in the AI favorites. Micron, Intel and AMD are all lower by more than 4%. Dell, Arista Networks, and SanDisk are down by about 7%.
Share this post
The shockingly fast PPI report didn’t dent the rally in fixed income.
The U.S. 10-year Treasury yield is at a session low, down 14.5 basis points to 5.044%. The iShares 20+ Year Treasury Bond ETF (TLT) is up 2% in pre-market trading, extending its rebound from recent lows to 5%.
The CME FedWatch tool now shows a 27% probability of a 25-basis-point rate hike at the Fed’s Oct. 28 meeting. At one point yesterday, the odds were nearly 45%.
Share this post
The September U.S. Producer Price Index rose a whopping 1.3%, far above August’s 0.4%, and blowing past forecasts for 0.5%.
On a year-over-year basis, PPI was higher by 6.3%, up from 5.4% in August, and above estimates for 5.3%.
The core PPI rose 0.7% versus 0.2% in August, and well above forecasts for 0.3%.
Year-over-year core PPI rose 5%, up from 4.6% in August, and higher than estimates for 4.4%.
Market reaction, for now, is rather muted:
Already under pressure on Thursday, bitcoin BTC$80,791.18 slumped about another $500 on the news to $80,500. Nasdaq 100 futures remain lower by 1% and bond yields remain sharply lower in response to growing concerns about the popping of the AI bubble.
In other economic news, initial jobless claims remained at historically low levels, edging up to 199,000 from 197,000.
Retail sales for September were stronger than forecast, rising 0.9% (ex-autos) versus the 0.5% estimate.
The October Empire State Manufacturing Index jumped to 25.5 from 7.6 in September, well above forecasts for a rise to 10.3.
Share this post
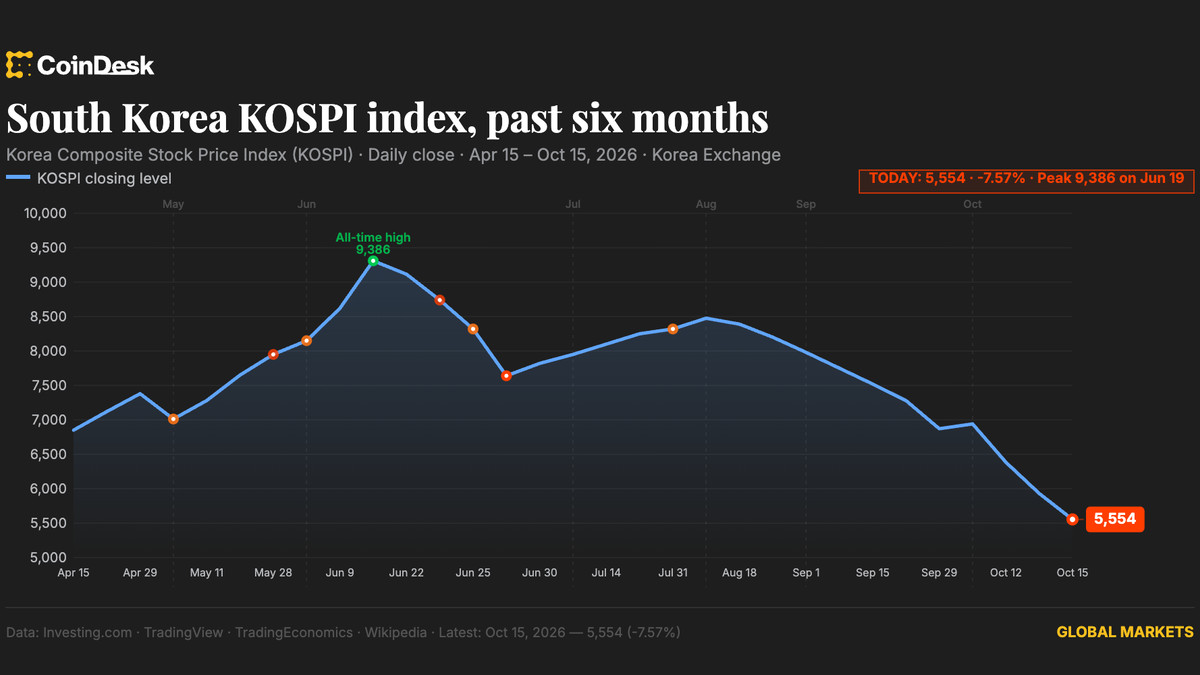
The chip-heavy (Samsung, SK Hynix) Kospi plunged another 7.5% overnight, as the U.S. slump Wednesday made its way around the globe.
According to Bespoke, the Kospi is now down 20% over the past seven trading days — the worst seven-day stretch since the Covid panic of March 2020.
The Kospi remains higher by 29% year-to-date.
Nasdaq 100 futures are lower by 1%, but have bounced a bit from their worst levels. S&P 500 futures are just marginally lower and DJIA futures are up 0.3%.
A fixed income rally is providing support. The U.S. 10-year Treasury yield is down another 10 basis points to 5.088%. At one point on Wednesday, following the fast CPI report, the 10-year yield spiked to 5.36%.
The September PPI report is coming up shortly.
Bitcoin is at $81,000, up a bit from its worst levels, but down 2.75% over the past 24 hours. Ether, solana, and XRP are lower by 4%-5%.
Share this post
Ether has recovered to $2,360, up from $2,314 hit early Thursday — its lowest level since Aug. 20, according to CoinDesk data.
ETH has pulled back sharply since topping $2,800 on Sept. 21, with the decline outpacing bitcoin’s.
A likely catalyst for the underperformance is elevated bond yields, which reduce the appeal of yield-generating DeFi protocols, a sector still largely built on Ethereum.
Share this post
The AI selloff continues led by CoreWeave (CRWV), which is down 4% in pre-market trading after tumbling more than 15% on Wednesday. Other AI infrastructure stocks are also under pressure, with Cipher Digital CIFR$8.8860 down 5%, TeraWulf WULF$10.54 falling 6% and IREN IREN$26.85 losing 4%.
Bitcoin has been dragged below $81,000, while gold appears to be the main beneficiary, rising more than 1% to reclaim $4,150 an ounce.
The U.S. Dollar Index (DXY) has surrendered some gains but remains above 102. Treasury yields continue to fall, with the U.S. 10-year yield now at 5.085%.
Attention now turns to producer price index (PPI) data, due within the next hour. Consensus forecasts point to a 0.5% monthly increase and a 5.3% annual rise. Following Wednesday’s hot consumer price inflation report, the release takes on added significance, with markets pricing in a 27% chance of a Federal Reserve rate hike at its October meeting.
Share this post
A hotter-than-expected U.S. inflation report briefly lifted bitcoin to nearly $84,000 on Wednesday, then sent it sliding to about $80,400 early Thursday. That’s just above last Thursday’s low of about $80,430. Bitcoin traded under $81,000, down 2.6% over 24 hours.
Core inflation, which strips out food and energy, rose to 2.6% against a 2.5% forecast. A hot print makes another Federal Reserve rate hike more likely, and that tends to lift the dollar and weigh on assets like bitcoin. The Fed meets again on Oct. 27–28.
AI stocks added to the pressure. Nasdaq 100 futures fell 1.2% after Anthropic told prospective investors its revenue grew $16.8 billion in the third quarter, a figure that showed growth slowing.
ZEC led crypto losses, down 11% to about $1,100. Ether dropped 5% to about $2,370, and U.S. spot bitcoin ETFs lost about $261 million on Wednesday, according to SoSoValue data.
A daily close below $80,400 would break the floor buyers have defended twice since last Thursday.

- 1
- 2
- 3
- 4
- 5
- 6
- 7
- 8
- 9
- 10


Sep 24, 2026
Why it matters:
Diversified RWA stablecoins sustain 5-7% yield from real credit as crypto funding compresses to ~4%. GENIUS pushes yield off-chain; TAM grows to $4B in 3 years.