The data proves it: Bitcoin doesn’t care about rising bond yields
Long-term, BTC ignores rising bond yields. In the short term, however, surging bond volatility could easily dampen crypto’s animal spirits.
By Omkar Godbole|Edited by Jamie Crawley
Share this article

Summary
As global bond yields rise, the usual narrative frames it as bearish for bitcoin
BTC$83,405.92
. Yet over most of BTC’s history, the asset has shown little to no consistent correlation with bonds.
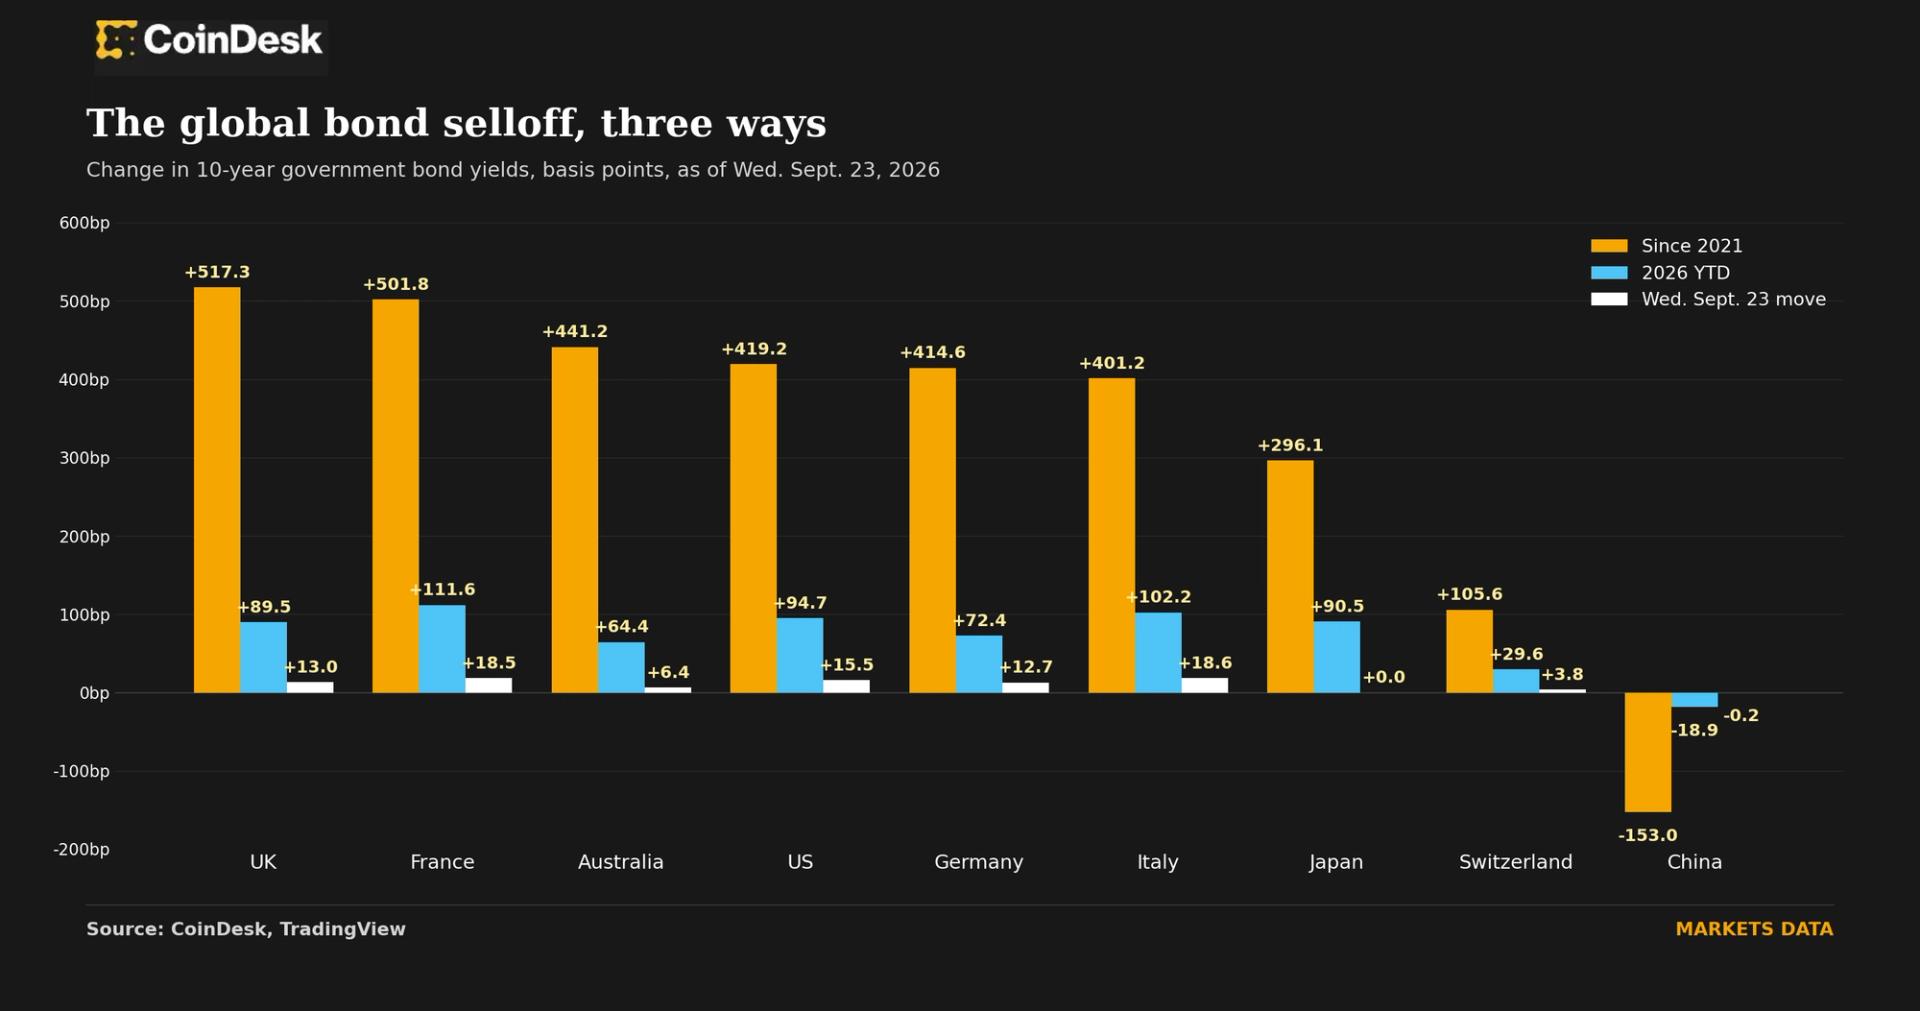
Yields snapped back into focus Wednesday. The U.S. 10-year jumped 15 basis points to its highest level since 2007, topping 5.13%, and pulled yields higher across the globe, as the feature image shows.
The standard interpretation is that as yields climb, the opportunity cost of holding non-yielding assets like bitcoin and gold rises, potentially pulling money toward bonds instead. In short, it’s a headwind, not a tailwind, for crypto.
That logic makes sense on paper. But correlations don’t back it up.
The 90-day correlation between bitcoin’s daily returns and the U.S. 10-year yield’s daily moves is just −0.18, according to data analyzed by CoinDesk. That’s close to zero and almost indistinguishable from no relationship at all.
Longer windows show the same thing, with the 180-day correlation at −0.06 and the 1-year figure at −0.03. Bitcoin is equally uncorrelated to yields of other nations.
Being this uncorrelated is actually a benefit. It means bitcoin can serve a similar role to other alternative investments in improving a portfolio’s risk-adjusted returns, as investment banks have argued for years. Crypto analysts suggest the same.
“Bitcoin’s near-zero correlation with U.S. Treasury yields is a genuine portfolio advantage because it suggests BTC is not simply trading as a duration or rates asset. Recent data shows the 90-day correlation between Bitcoin’s daily returns and the U.S. 10-year yield at around -0.17, with the relationship at times moving even closer to zero,” Lacie Zhang, research lead at Bitget Wallet, told CoinDesk.
Bitcoin’s broader performance backs this up too. It’s up 191% since 2021, and hit a record price of $126,000 last October. That happened even as 10-year yields climbed more than 500 basis points in the U.K. and France, and over 400 in the U.S., Australia, Germany, and Italy over the same stretch.
Japanese and Swiss yields have risen by 296 and 105 basis points, respectively, while China’s have dropped as the country has been battling deflation.
Being broadly uncorrelated doesn’t necessarily insulate bitcoin from short-term pain, especially when the pain comes from the bond market volatility itself rather than the level of yields.
A sudden spike in bond market turbulence, particularly in Treasuries, which underpin global finance, can tighten financial conditions, make credit more expensive, and trigger broader risk aversion.

The MOVE Index, which tracks expected turbulence in Treasury notes, surged 21% to 95 points on Wednesday, its highest level since April 1. That helps explain bitcoin’s pullback from $87,200 to $83,500 on Wednesday, though the market may also have simply been looking for a reason to pull back after the recent steep run higher.
If Treasury volatility persists or climbs further, bitcoin could correct more.
Yields’ lift on Wednesday was led by U.S. data, not fiscal fear.
S&P Global’s flash U.S. Composite PMI rose to 58.4 in September, the highest reading since July 2021, up from 56.0 in August, with business activity expanding at its fastest pace in more than five years alongside a buildup in inflationary pressure.
That data reinforced expectations that the Fed will need to keep hiking after the September rate increase of 25 basis points. The 10-year and two-year yields both jumped on it.
But a closer look at the feature image shows France’s yield actually rose more than the U.S.’s on Wednesday, even though it was U.S. data driving the move. The U.K.’s yield also rose nearly as much as the U.S. Per Robin Brooks, Senior Fellow at the Brookings Institution and former chief economist at the IIF, the same held for Italy and Greece.
“What happened today is that we got strong data for the U.S. and then fiscally vulnerable places caught on fire,” Brooks wrote in a Substack post published Wednesday.
This isn’t new, according to Brooks. Markets have been penalizing high fiscal debt countries for a while now.
Japan was in the pole position at the end of 2025 with the debt-to-GDP at over 200%, with the U.S. at 123.8%, according to Statista. France and the U.K. were at 115% and 102%, respectively followed by China at 100%.
Meanwhile, Switzerland’s federal debt was just 16% of its GDP, a bright spot. This, coupled with a more measured rise in its 10-year bond yield over the years, has led some analysts to call the Swiss franc (CHF) a haven that’s steadily replacing the Japanese yen as the favored carry currency.
For bitcoin, the story is simple. The forces spooking bond markets — fiscal credibility, growth and inflation, in Paris, London or New York — are being priced into yields and affecting fiat currencies, yet they haven’t shown up in bitcoin’s price action over the years.
Related Assets

- 1
- 2
- 3
- 4
- 5
- 6
- 7
- 8
- 9
- 10


Sep 15, 2026
Why it matters:
As stablecoins move into regulated finance, APAC is becoming a key proving ground. This report maps the region’s rules, use cases, and RLUSD’s role.